time-aware ML · uncertainty · portfolio research
Regime Residual Portfolio
A residual-alpha forecasting and portfolio-construction research pipeline built around walk-forward evaluation, validation embargoes, MC Dropout uncertainty and transaction-cost awareness.
Problem
Financial backtests are unusually easy to contaminate with future information or frictionless assumptions. The project focuses on whether residual-return signals can be studied with a time-aware pipeline that separates prediction from portfolio decisions.
What I built
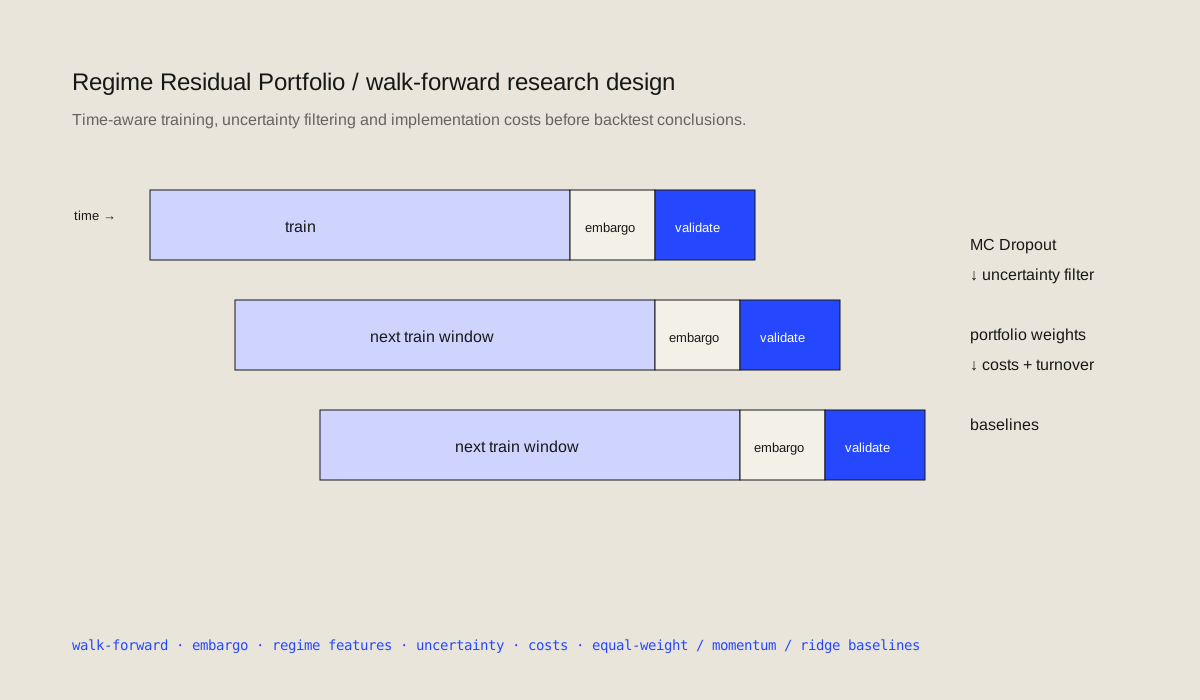
The workflow creates residual-alpha targets and market-regime features, trains models in rolling windows with an embargo, estimates predictive uncertainty with MC Dropout, filters signals, constructs monthly portfolios and evaluates turnover and transaction costs against explicit baselines.
Temporal leakage controls and explicit baselines are part of the evaluation design.
Engineering decisions
Where the project becomes more than a demo.
The details that matter are usually in the constraints: who is allowed to decide, what gets measured, what is kept separate, and how failure is represented.
Make time the first constraint.
Train and validation windows move forward and use an embargo to reduce contamination across adjacent periods.
Separate prediction from portfolio logic.
Model outputs are inputs to a downstream signal-filtering and allocation layer rather than being treated as trades by default.
Evaluate uncertainty and friction.
MC Dropout estimates predictive uncertainty, while turnover and costs keep the backtest closer to an implementable decision process.
Evidence
What the repository actually supports.
equal weight, momentum and ridge-based prediction
Dropout sampling used to filter uncertain signals
turnover and transaction friction are tracked in the evaluation
Limits
What I am not claiming.
- The repository explicitly does not claim guaranteed alpha or future investment performance.
- Results are sensitive to universe construction, costs, non-stationarity and data quality.
- The main signal of the project is time-aware ML methodology rather than a single backtest number.
Signal